ServicesMotor Truck Cargo Insurance
Motor Truck Cargo Insurance in Lithia Springs
Motor truck cargo insurance pays for the freight you are hauling when it is damaged or stolen in your care. We match the limit, deductible and commodity list to the loads you actually pull, so a claim is not denied over a line you never read.
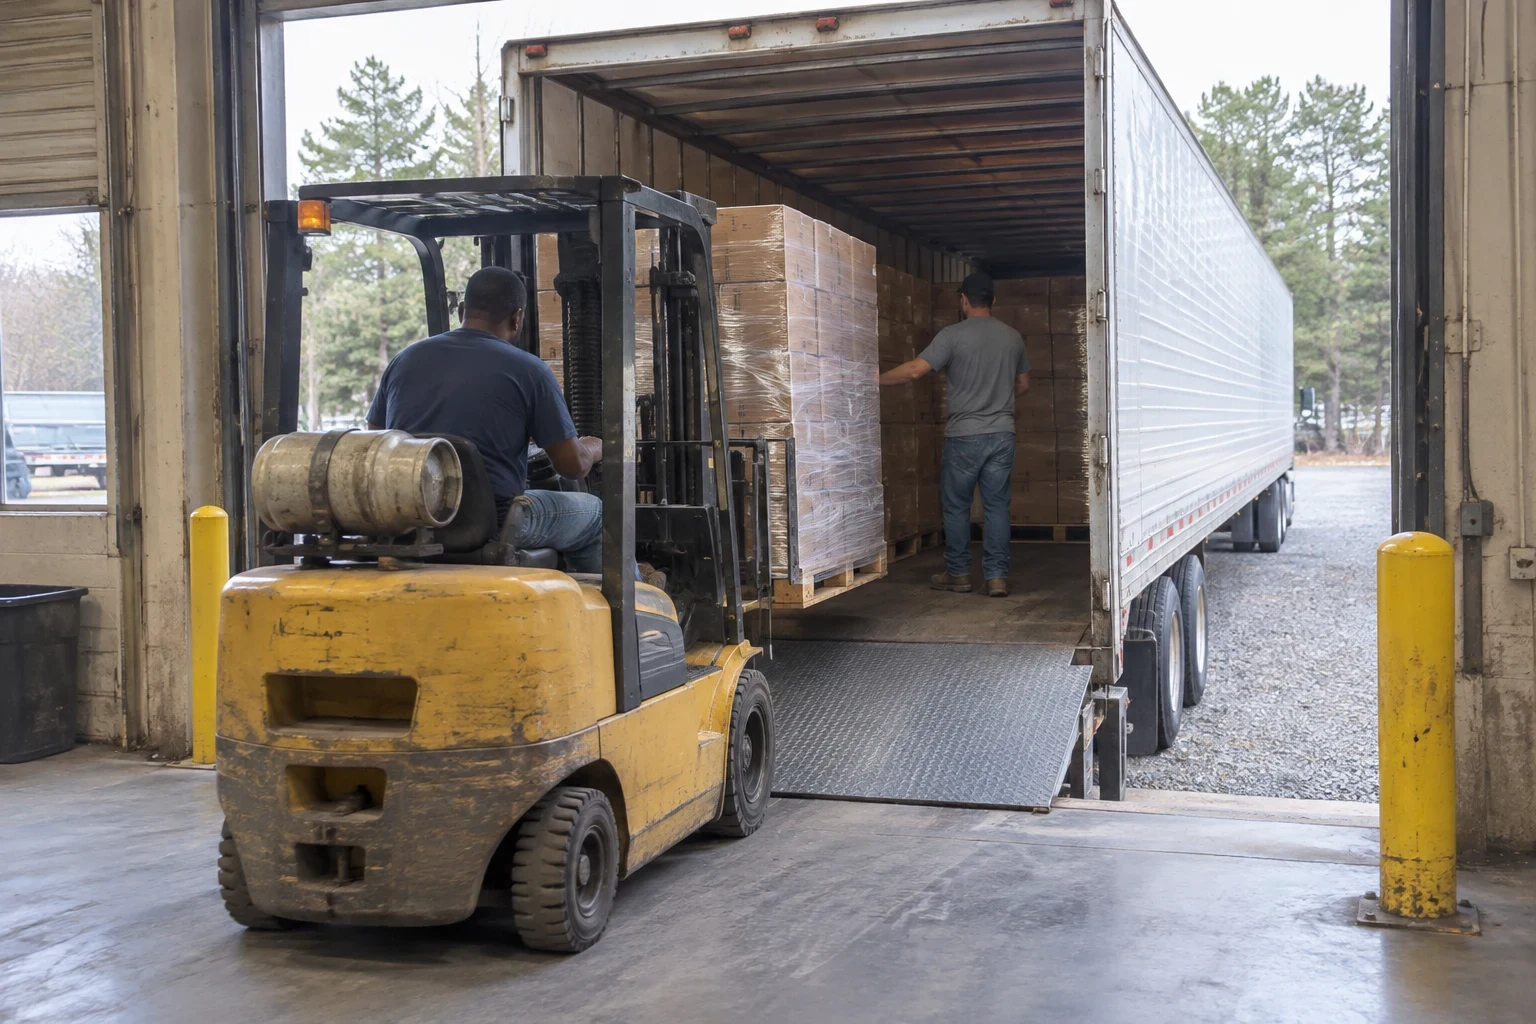
What cargo coverage does and when you need it
Your auto liability policy covers damage you do to other people. Your physical damage policy covers your truck and trailer. Neither pays for the load. Motor truck cargo insurance fills that gap: it responds when freight is lost, stolen or damaged by a covered cause such as a collision, fire, overturn or theft while it is in your custody.
Federal rules do not require cargo coverage for most general freight carriers. In practice, nearly every broker and shipper does. If your certificate of insurance does not show a cargo limit that meets their contract, you do not get the load.
The real risk is in the details. Cargo forms differ on which commodities are excluded, whether reefer breakdown is covered, and what happens if the truck is left unattended. We read those terms with you before you sign.
What we set up on a cargo policy
A limit that fits your contracts
We look at the broker and shipper agreements you run under and set a per-load limit that meets them. We also check the value of your typical load, because a limit below that value leaves you paying the difference.
Commodity review
Many cargo forms exclude or restrict items like electronics, tobacco, alcohol, pharmaceuticals and high-value metals. We list what you haul and confirm each commodity is covered, not just your main one.
Reefer breakdown, if you pull temperature freight
Spoilage from a refrigeration unit failure is usually not covered unless reefer breakdown is added. We explain what that endorsement requires, such as maintenance records and temperature logs.
Theft and unattended vehicle terms
Some policies only cover theft if the truck was locked, alarmed or parked in a secured lot. We point out those conditions so you know how to park to stay covered.
Certificates of insurance for brokers
When a broker asks for a certificate showing your cargo limit, we issue it with the right certificate holder named. You can call us for each new broker setup.
Signs your cargo coverage needs a look
- A broker rejected your certificate
- If a load board setup bounced because the cargo limit was too low or the form was missing, the policy no longer fits the freight you are being offered.
- You changed what you haul
- Moving from dry van general freight to produce, electronics or building materials can put you on the wrong side of an exclusion. The policy has to be updated before the first load, not after a claim.
- You started pulling a reefer
- A dry freight cargo policy will not pay for a spoiled load after a compressor or fuel failure. That needs a reefer breakdown endorsement.
- Your loads are worth more than your limit
- A single trailer of consumer goods or copper can exceed a standard limit. If your typical load value is above your per-load limit, you carry the shortfall yourself.
- You have never read the exclusions
- Most denied cargo claims come down to an exclusion or condition the carrier did not know about. If you cannot name yours, call us and we will go through them.
How getting a cargo quote works
- 1
Phone or video call
We start with your operation: DOT number, MC authority, equipment type, the commodities you haul and the lanes you run. Most of this takes a short call.
- 2
Load value and contract check
You send the broker or shipper requirements you work under. We compare them to your highest and typical load values to pick a limit and deductible.
- 3
Quotes with the terms side by side
We bring back options and explain where they differ: excluded commodities, theft conditions, reefer coverage and deductible. You see the tradeoffs, not just the premium.
- 4
Binding and certificates
Once you choose, we bind the policy and issue certificates of insurance to the brokers who need them. Changes later, such as a new commodity or trailer, are handled by phone.
What moves the price of cargo insurance
Cargo premiums are driven mostly by what is on the trailer and how likely it is to be stolen or spoiled. Your loss history and the limit you choose matter too. Here is what underwriters weigh.
- Commodities hauled
- Building materials and general dry freight usually rate lower. High-theft goods like electronics, beverages and metals, or perishables in a reefer, rate higher because claims are more frequent and more expensive.
- Limit and deductible
- A higher per-load limit costs more. A higher deductible lowers the premium, but you pay that amount out of pocket on every claim.
- Reefer breakdown and other endorsements
- Adding reefer breakdown, higher theft limits or coverage for specific excluded commodities each adds to the premium.
- Loss history and experience
- Prior cargo claims raise the rate. New authorities have no track record, so underwriters lean harder on equipment, commodity and driver experience.
- Radius and lanes
- Long-haul lanes and overnight stops raise theft exposure compared with short regional runs that return to a secured yard.
Cargo insurance questions
- Isn't cargo covered by my auto liability policy?
- No. Primary auto liability pays for injury and damage you cause to others. The freight on your trailer is your responsibility to the shipper, and only a cargo policy pays for it. Physical damage insurance covers the equipment, not the load.
- How much cargo coverage do brokers want?
- It depends on the broker and the freight. Many publish a minimum cargo limit in their carrier packet, and high-value loads may require more. Send us the packets you work under and we will set a limit that clears them.
- Will my policy pay if my truck is stolen at a truck stop?
- It depends on the theft conditions in your form. Some policies require the truck to be locked with keys removed, and some exclude theft from an unattended vehicle unless it is in a secured lot. We tell you exactly what your policy requires before you bind it.
- Does cargo insurance cover spoiled produce?
- Only if you have reefer breakdown coverage and the loss came from a covered cause, usually a mechanical failure of the refrigeration unit. Insurers often ask for maintenance records and temperature logs at claim time, so keep them.
- I run a box truck or hotshot rig. Do I still need cargo coverage?
- If you haul freight for brokers or shippers, they will almost always ask for it. The limit and commodity list just need to fit smaller loads. We can set it up alongside your box truck insurance or hotshot truck insurance.
Make sure your cargo policy covers the loads you pull
Tell us what you haul and who you haul it for. We will walk through limits, exclusions and premium options in plain terms.